Short Term CD Ladder
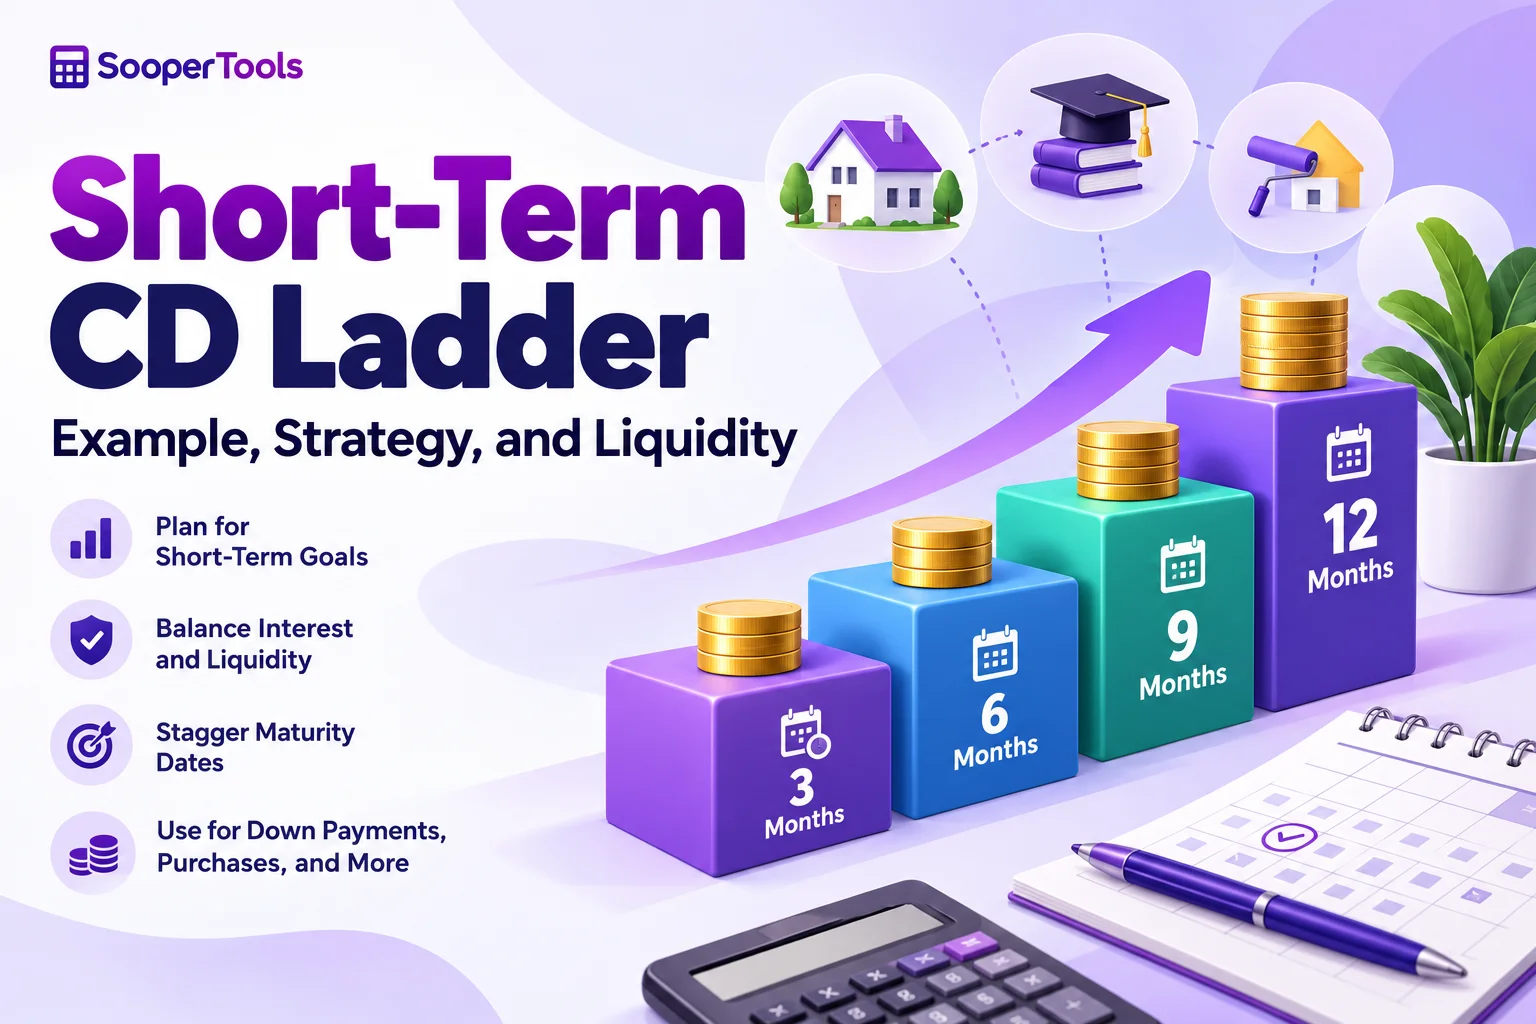
Table of Contents
Short Term CD Ladder Strategy for Liquidity and Savings Goals
A short term CD ladder is a savings strategy that divides money among certificates of deposit (CDs) with different, relatively short maturity dates. It can help you plan when portions of your savings become available for expenses such as a home down payment, a vehicle purchase, tuition, or home improvements. Instead of locking your entire balance into one CD, you organize the maturity schedule around the dates you expect to need the money.
The goal is to balance interest earnings with access to savings. A short term ladder can create a structured schedule for planned expenses, but it does not make every CD instantly accessible. You generally need to wait for a CD to mature or follow its early withdrawal rules, which may involve a penalty.
Key point: Match each CD maturity date to your expected cash needs. Keep enough money in an accessible account for emergencies and expenses that may arise before a CD matures.
What Is a Short Term CD Ladder?
A certificate of deposit is a deposit account that generally pays interest in exchange for leaving money deposited for an agreed period. Depending on the financial institution, CD terms may include periods of several months or several years. The maturity date identifies when the agreed term ends.
A short term CD ladder uses multiple CDs with staggered maturity dates over a relatively short planning horizon. For example, a saver might consider three month, six month, nine month, and twelve month CDs if those terms are available and fit the intended goal.
Vanguard describes a short term CD ladder, also called a mini CD ladder, as a structure using CDs with shorter maturities for goals that are closer in time. The precise terms available and suitable maturity schedule depend on the financial institution and the saver’s needs. Read Vanguard’s explanation of CD ladders.
The term mini CD ladder generally refers to a smaller or shorter term ladder. It is not a standardized banking product with a universally required number of CDs, minimum deposit, or maturity schedule. The right structure depends on how much you want to save, when you need the money, and which CD terms your financial institution offers.
For the broader strategy, including longer maturity schedules and general CD ladder concepts, see the SooperTools CD Ladder Guide.
How to Build a Short Term CD Ladder for Liquidity
When planning how to build a short term CD ladder for liquidity, start with the dates when you will need the money. Do not begin by choosing CDs solely because they advertise attractive annual percentage yields (APYs). A CD that matures after your payment is due may not be appropriate for that portion of your savings.
1. Set a Clear Savings Goal and Deadline
Identify what you are saving for, how much you expect to need, and when payments are due. A home purchase, for example, may involve an initial deposit, closing costs, moving expenses, and later purchases. A vehicle purchase might have one primary payment date. Different spending schedules can require different maturity arrangements.
Write down the expected amount and date for each major expense. If your deadline could change, leave a suitable margin rather than scheduling a CD to mature at the last possible moment.
2. Keep Emergency Funds Accessible
Separate emergency savings from money intended for predictable, planned expenses. Emergency cash may be needed without warning, whereas a CD is designed around a fixed term. The Consumer Financial Protection Bureau explains why emergency savings should remain accessible for unexpected costs in its guide to building an emergency fund.
Only allocate to CDs money you can reasonably leave deposited for the selected terms. This reduces the chance of paying an early withdrawal penalty because an unexpected expense arises.
3. Choose Maturity Intervals That Fit Your Timeline
List your payment dates on a calendar, then compare them with the available CD terms. Three, six, nine, and twelve month maturities can be useful examples, but not every institution offers every interval. Your selected maturity dates should allow you to access the funds before they are required.
For a single expense due in twelve months, a twelve month CD may be more straightforward than creating several earlier maturities, provided the money will not be needed before maturity. A staggered ladder may be more useful when you have multiple planned payments or deliberately want earlier opportunities to review your savings.
4. Divide the Deposit into Suitable Portions
Choose how much to allocate to each CD. Equal deposits are straightforward to manage, but they are not essential. You may need a larger amount to mature before a major expense and smaller amounts for later payments.
Compare APY, term, minimum deposit, interest payment arrangements, early withdrawal penalties, and renewal rules. Review the complete account terms before opening a CD. The CFPB’s CD guidance explains important considerations when comparing CD accounts.
5. Review Each Maturity Before Reinvesting
When a CD matures, decide whether the proceeds are needed soon, should move into an accessible savings account, or can be placed into another CD. Consider the upcoming spending schedule and the rate and maturity of any new CD before reinvesting.
Some CDs renew automatically if you do not give instructions within the financial institution’s specified period. Check the maturity notice and renewal terms so that money you need does not unintentionally become committed to another term.
The SooperTools CD Ladder Calculator can help organize deposits and compare a planned maturity schedule.
Illustrative Maturity Schedule
Suppose you have $20,000 earmarked for planned expenses during the next twelve months. You expect to need portions of the money at different times, so you consider placing $5,000 into each of four CDs with different maturity dates.
Example: Organizing $20,000 Across Four CDs
This example assumes the financial institution offers the terms shown. It illustrates how maturity dates can be organized; it does not represent a current rate offer or a guarantee of earnings.
| CD | Deposit | Initial term | Maturity | Possible purpose |
|---|---|---|---|---|
| CD 1 | $5,000 | 3 months | Month 3 | First planned payment |
| CD 2 | $5,000 | 6 months | Month 6 | Second planned payment |
| CD 3 | $5,000 | 9 months | Month 9 | Third planned payment |
| CD 4 | $5,000 | 12 months | Month 12 | Final planned payment |
| Total | $20,000 | Four scheduled maturities over twelve months |
If these portions correspond to separate expenses, the schedule may help align funds with payment dates. At each maturity, you can use the proceeds for the relevant expense or reassess how to hold the money for a later date.
What If You Need All the Money at the End of Twelve Months?
The schedule above does not automatically make the entire $20,000 available in month twelve, because three portions mature earlier. If you need the full balance on one specific date, you must plan for the earlier proceeds.
For example, the proceeds from earlier maturities could remain in an accessible savings account until the target date. Alternatively, you may consider reinvesting them in suitable shorter term deposits that mature before that date, if available and consistent with your plans. Reinvestment introduces new terms and rates, so confirm those details rather than assuming the original CD conditions will continue.
Important distinction: Staggered maturity dates create opportunities to access portions of your savings at different times. They do not guarantee that your entire balance will be available on a particular date unless every portion has been planned to mature or remain accessible by then.
Your actual interest earnings will depend on each deposit, its APY and term, the interest payment or compounding arrangement, and any applicable charges. Because no current APY has been assumed in this example, it does not estimate or promise a specific return.
When a Short Term CD Ladder Strategy Can Be Useful
A short term CD ladder strategy can be helpful when the purpose of the savings and the approximate spending dates are known in advance. It is less suitable when you may need the full balance immediately or when the timing of your expenses is highly uncertain.
Saving for a Home Down Payment
If you plan to buy a home within the next year or two, list the likely dates for the deposit, closing costs, moving expenses, and other payments. Keep the amounts that may be needed early in accessible accounts. Consider CDs only for portions that can remain deposited until their maturity dates.
Preparing for a Vehicle Purchase
If you have a target purchase date, compare CD terms that mature before it. Keep in mind that the final price or purchase date may change. Do not place the entire purchase budget into CDs if you may need part of it for an earlier deposit or unexpected cost.
Planning Tuition or Home Improvement Payments
Some goals involve a sequence of bills instead of one final payment. A maturity schedule can help organize savings around those dates. Estimate when each payment is due and how much it requires, then choose terms that provide sufficient time to access the funds.
Starting With a Mini CD Ladder
A mini CD ladder for beginners can be a manageable way to learn how maturity schedules work. Start with a small number of CDs, keep a simple record of each deposit and maturity date, and add complexity only when it serves a real goal.
There is no universal number of CDs or minimum balance that makes a ladder a mini ladder. The useful considerations are the duration of the plan, the amounts involved, and the work required to manage it.
Short Term CD Ladder vs a Traditional CD Ladder
Both strategies spread savings across different maturity dates. Their main difference is the time horizon and how frequently portions of the balance become available.
| Feature | Short Term CD Ladder | Traditional CD Ladder |
|---|---|---|
| Planning horizon | Near term goals over months or a few years | Often designed around a longer period |
| Maturity intervals | May use shorter terms, such as 3, 6, 9, or 12 months | May use annual intervals or longer terms |
| Access to funds | Earlier maturities may match upcoming payments | Access depends on the selected terms and schedule |
| Key planning concern | Aligning every maturity with a near term cash need | Balancing access, longer terms, and future reinvestment |
| Typical use case | Down payments, planned purchases, tuition, or renovations | Funds that can remain committed over a longer horizon |
Neither approach is automatically better. A short term ladder may offer a more suitable schedule for near term goals, while a longer ladder may fit savings that are not required for several years. Choose the structure according to the dates and amounts you actually need.
If your primary concern is emergency cash rather than a known spending schedule, see the CD Ladder Emergency Fund Guide. It covers the separate question of balancing emergency access with money committed to CDs.
Risks and Limitations to Understand
Early Withdrawal Penalties
Many CDs impose a penalty if you withdraw money before maturity. The amount depends on the account terms and may reduce the interest you earned. Read the disclosure before opening a CD and consider whether you can leave that portion of your savings untouched for the whole term.
Reinvestment Risk
When a CD matures, a new CD may offer a higher or lower APY than the one that just ended. Shorter terms give you more opportunities to reassess your choices, but future rates are uncertain. Do not build your budget around receiving the same rate every time you reinvest.
Inflation and Purchasing Power
Interest earnings may not keep pace with rising prices. For a short term savings goal, the ability to access money when it is needed may matter more than the possibility of earning a somewhat higher return. Compare the expected return with your timeline and the purpose of the funds.
Liquidity Is Scheduled, Not Immediate
A ladder helps plan when portions of your savings mature. It does not turn a CD into an everyday transaction account. If you might need money without warning, keep the necessary reserve in an accessible account rather than relying on a future CD maturity or accepting an early withdrawal penalty.
Deposit Insurance Limits
Eligible deposits at an FDIC insured bank are generally insured up to $250,000 per depositor, per insured bank, for each account ownership category. The FDIC combines eligible deposits in the same ownership category at the same bank when determining coverage, so the limit is not automatically available separately for every CD. Your actual coverage depends on how the accounts are owned and the applicable rules.
Review the FDIC’s explanation of deposit insurance and verify your own coverage when comparing institutions. Eligible credit union deposits may be covered by NCUA share insurance under its applicable rules and limits.
How to Compare Short Term CD Offers
Compare offers using the same deposit amount and a similar time horizon where possible. The advertised rate is only one part of the decision; the term and withdrawal conditions must also fit your plans.
- Annual percentage yield (APY): Compare APYs on a consistent basis. Actual interest earned still depends on the amount deposited, the CD term, and how interest is paid or compounded.
- Maturity date: Confirm the precise date the CD ends and make sure the proceeds will be accessible before the planned payment.
- Minimum deposit: Check that the required opening amount fits your planned allocation.
- Early withdrawal penalty: Understand the potential cost if your needs change before maturity.
- Automatic renewal: Review whether the CD renews automatically, the notice period, and how to give different instructions.
- Institution and insurance: Verify the bank or credit union and check the applicable deposit insurance coverage for your accounts.
Our CD Ladder Rates Guide provides additional context for comparing rates and terms. Verify current offers and account conditions directly with the financial institution before committing your money.
Related Tools
Use these calculators to organize your CD savings and compare deposits.
- CD Ladder Calculator — Plan CD deposits and maturity dates across a ladder.
- CD Calculator — Estimate CD interest and maturity value using your deposit, rate, and term assumptions.
Frequently Asked Questions
1. What Is a Short Term CD Ladder?
A short term CD ladder divides savings among CDs with different, relatively short maturity dates. It can help align portions of your savings with planned expenses while earning interest under each CD’s terms.
2. How Do I Build a Short Term CD Ladder for Liquidity?
Identify your savings goal and payment dates, set aside accessible emergency savings, choose CD terms that mature before the relevant expenses, divide the remaining funds into suitable deposits, and review each maturity before spending or reinvesting.
3. How Should I Choose CD Maturity Dates?
Start with the dates and amounts of your planned expenses. Choose CD terms that allow the relevant money to mature before each payment is due. If you need the full balance on one date, account for any earlier maturing proceeds and keep funds accessible when required.
4. What Is a Mini CD Ladder?
A mini CD ladder generally means a smaller or shorter term CD ladder. It is a descriptive term rather than a standardized product with a universal minimum deposit or required number of CDs.
5. Is a Short Term CD Ladder Suitable for a Down Payment?
It may be suitable for the portion of a down payment that can remain deposited until its scheduled maturity. Keep amounts needed earlier accessible, and ensure the CD matures before the money is due. If the purchase date is uncertain, avoid committing the entire budget to CDs.
6. Can I Withdraw Money From a CD Before Maturity?
Early withdrawal is subject to the CD’s account terms and may incur a penalty. A ladder provides scheduled opportunities to access money, not unrestricted immediate access to every deposit. Review the withdrawal rules before opening an account.
7. Is a Short Term Ladder Better Than a Traditional CD Ladder?
It depends on your time horizon. A short term ladder may suit planned expenses over the next several months or years, while a traditional ladder may suit funds that can remain deposited longer. Compare the maturity schedule with the dates you need the money.
8. Should I Reinvest a CD When It Matures?
Reinvest only after reviewing upcoming expenses, the new APY and term, and the new maturity date. If you need the money soon, an accessible savings account may be more appropriate than another CD.
9. Are Short Term CDs Insured?
Eligible CDs at FDIC insured banks are generally covered by FDIC deposit insurance within the applicable limits. Eligible share certificates at federally insured credit unions may be covered by NCUA share insurance. Verify the institution and calculate coverage across your combined deposits and ownership categories.
10. Does a Short Term CD Ladder Guarantee a Specific Return?
No. A CD’s contract specifies its rate and terms for the agreed period, but future rates on replacement CDs may change. Your actual earnings also depend on the deposit, APY, interest arrangements, and any applicable penalties or fees.
Final Considerations
A short term CD ladder can help organize savings when you know roughly when your money will be needed. Its main benefit is a planned series of maturity dates, not a guarantee of maximum returns or immediate access. A useful short term CD ladder strategy starts with your spending timeline, keeps emergency cash accessible, and uses CD terms that fit the goal.
Before opening CDs, confirm each maturity date, review early withdrawal and renewal rules, compare available APYs, and check deposit insurance coverage. Revisit the schedule if your expected expenses change. The right ladder is the one that fits your cash needs without requiring you to take avoidable withdrawal penalties or rely on uncertain future rates.
This article provides general educational information and is not individualized financial advice.
Sources and Further Reading
- Consumer Financial Protection Bureau: What Is a Certificate of Deposit? — CD terms, maturity dates, and account conditions.
- Federal Deposit Insurance Corporation: Understanding Deposit Insurance — Coverage limits and account ownership categories.
- Vanguard: CD Ladder — What It Is and How to Build One — Ladder structure and shorter term maturity considerations.